STRATEGIC FINANCE & ADVISORY SERVICES

Financial clarity for the business you’ve built.

Know your numbers. Make better decisions. Keep more of what you earn.

ATA Advisory Group pairs an accountable advisor with ATA Metrics, so owners see where the business stands, what lies ahead and what to do next.

forecast_by_month · sample company$ thousands · Nov 2026 – Oct 2027
Sample company forecast by month, in thousands of dollars, November 2026 to October 2027. June to August are the squeeze months.
LineNovDecJanFebMarAprMayJunJulAugSepOct
Own cash100.061.857.5100.091.266.429.68.859.059.8100.0100.0
Borrowed on linenone+13.2+17.4nonenone+8.6+45.4+65.9nonenonenonenone
Repaid✓ (30.1)nonenone✓ (20.5)nonenonenonenonenonenone✓ (48.0)✓ (12.2)
Month-end cash100.075.075.0100.091.275.075.074.859.059.8100.0100.0
Below minimumnonenonenonenonenonenonenone(0.2)(16.0)(15.2)nonenone
Line balance19.933.050.530.030.038.684.1150.0150.0150.0102.089.8
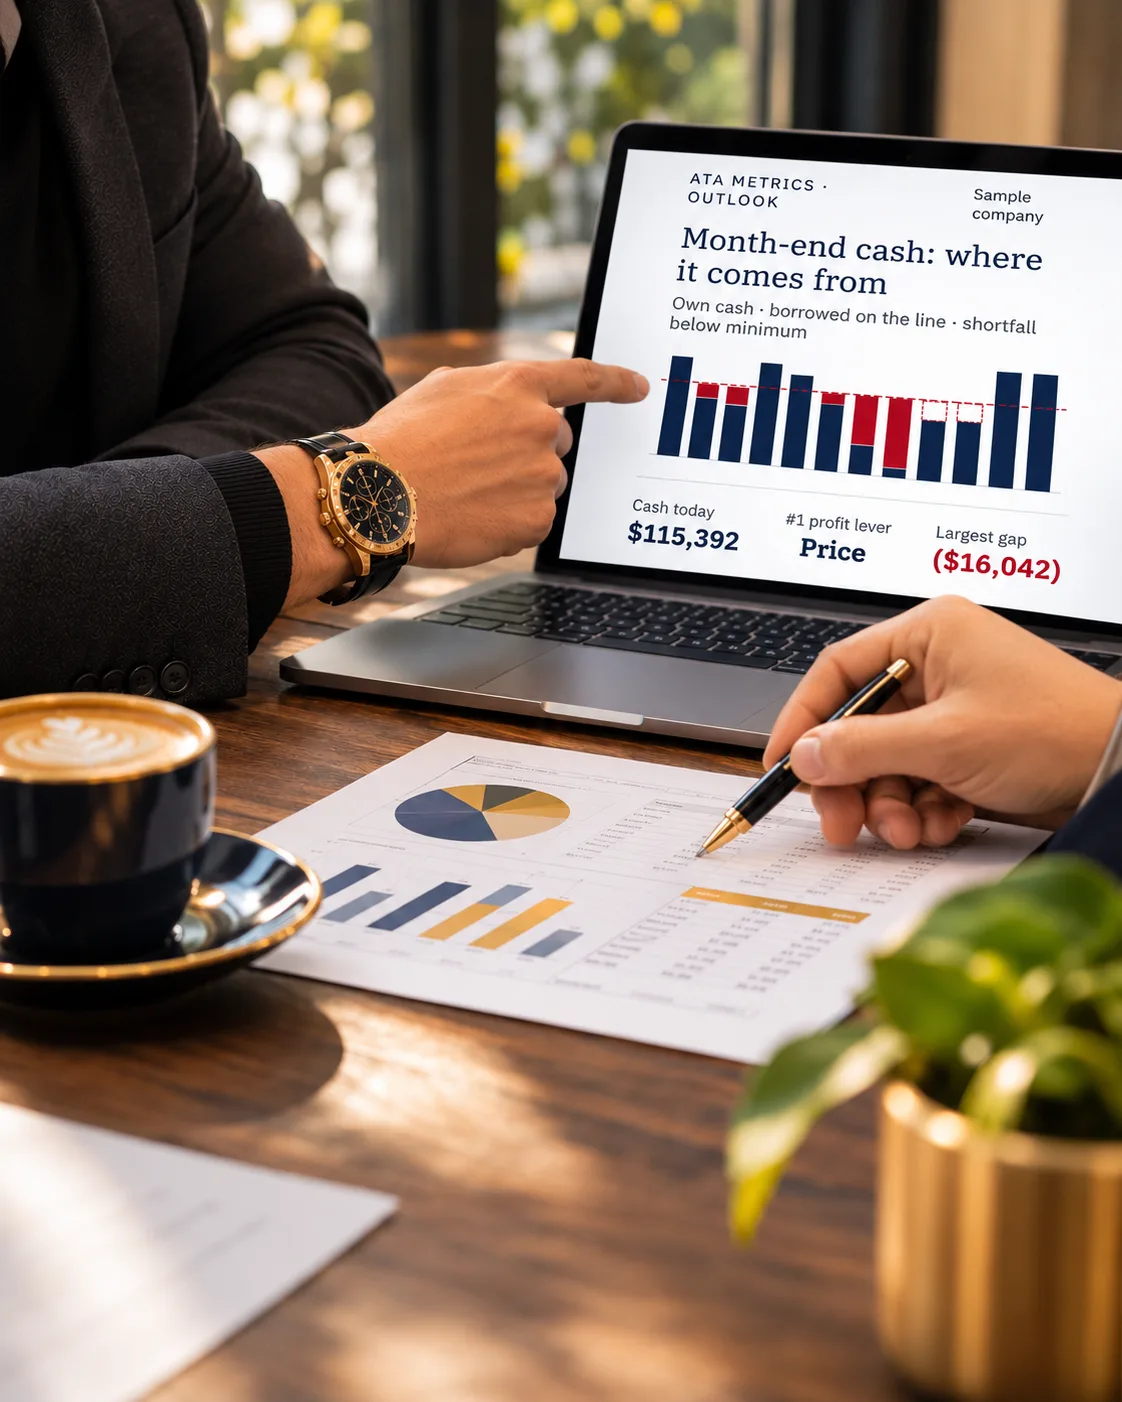
ATA METRICS · OUTLOOKSample company

Month-end cash: where it comes from

Own cash · borrowed on the line · shortfall below minimum
Cash today
$115,392
#1 profit lever
Price
Largest gap
($16,042)
  • WORKS WITH YOUR SYSTEMS
  • QuickBooks Online
  • Your bank
  • Payroll exports
  • Excel
  • Read-only — we never move money or change your books
ATA METRICS · CASH VIEWSample company

Next 13 weeks of cash

Line = most likely · shaded = if customers pay later than usual
$75K minimumNov 2Dec 14Jan 25
Most likely low: $33,764
week of Jan 25
If collections slow: $1,409
the credit line covers the gap
WHY OWNERS CALL US

You’re great at what you do. The numbers shouldn’t be a guessing game.

Owners make the big calls — pricing, hiring, borrowing — with last month’s bookkeeping report and instinct. Generic advice rarely fits, and a full-time CFO costs $200,000 or more.

We show you what is coming — a cash squeeze in late January, a margin slipping on installs — weeks before it arrives, and what to do about it.

SCENARIOS

Test the big decision before you make it.

Ask a question in plain English. ATA runs it through your own numbers, shows what changes, and lets you switch the levers on and off. Your advisor reviews it with you before you commit.

ASK ATASummit Comfort HVAC · sample
You asked
Can we afford another technician this summer?
ATA answered · from your numbers
As the plan stands, no: by July your credit line is maxed and cash still falls $16,042 short. With prices up 3% and customers paying 5 days sooner, the line peaks at $91,768 — the hire fits, with $58,232 of room left.
CREDIT LINE NEEDED AT THE SUMMER PEAK
CREDIT LIMIT $150K$166.0K−$74.3K$91.8KPLAN + NEW HIREPRICE + COLLECTIONSWITH BOTH CHANGESSHORT
  • NEW TECHNICIAN (on)
  • PRICE +3% (on)
  • COLLECT 5 DAYS FASTER (on)
THE ROLE HAS CHANGED

The CFO’s job has moved from reporting the past to steering what comes next.

Higher borrowing costs, tighter margins and lenders asking for more have raised the stakes on every financial decision. Owners need forward-looking judgment — on cash, pricing, hiring and financing — more than another report.

Most growing businesses need that judgment without the cost of a full-time executive. Our engagements are a standing monthly advisory relationship, scoped to each business after its Health Check and priced at a fraction of a full-time CFO.

A technician loading tools into a service van at sunrise
OUR APPROACH

Three parts, one relationship.

Technology does the gathering and the arithmetic. Your advisor does the thinking — and is accountable for it.

An accountable advisor

A senior finance professional who knows your business, reviews every figure and stands behind every recommendation.

ATA Metrics

Your books and bank data, organized around the measures that matter in your industry — with forecasts and early warnings.

A monthly rhythm

Review, decide, act. A standing meeting and a written plan, so decisions are made deliberately — not under pressure.

WHAT OWNERS GAIN

Fewer surprises. Better decisions.

  1. See cash problems weeks early

    Invoice-level forecasts show where the pressure points are — and what your credit line can and cannot cover.

  2. Know the one move worth the most

    Each month, the levers ranked in dollars: price, volume, cost and overhead.

  3. Numbers built for your industry

    The figures that matter for a contractor, a restaurant or a clinic — with reporting lenders and boards respect.

  4. Someone in your corner

    A standing monthly meeting, a written plan and follow-through, so decisions actually get made.

A MONTH WITH ATA

What working together looks like.

Moments from a typical month — the kind of answers that arrive before you have to ask. Sample company.

MONDAY · 7:00 AMATA Watch → owner

Cash, checked before the week starts

Your 13-week view moved. July runs about $16,000 below your $75,000 minimum because the credit line is fully drawn by June. Three fastest fixes: collect the two largest late invoices, move one supplier payment within terms, ask the bank about a higher limit.
Arrives by email and in ATA Metrics — no login needed to read it.
CLOSE DAYAdvisor review

What moved — down to the invoice

Gross margin slipped 2.1 points this month. Most of it traces to materials on equipment installs: three supplier invoices at the new price list. Service calls held steady.
Every line links back to the transactions behind it.
BEFORE THE BANK MEETINGOwner request

A lender-ready package, from this month’s numbers

Statements, debt schedule, coverage with the new loan payment (1.51×), a stress test at 20% lower cash flow, and the open items the bank will ask about — prepared from your own records.
You send it; we never contact the lender on your behalf.
HOW ATA COMPARES

The judgment of a CFO, without the full-time cost.

An honest view of the usual options. Many owners use more than one — we work alongside them.

How ATA Advisory Group compares with a bookkeeper alone, software only and a full-time CFO
BOOKKEEPER ALONESOFTWARE ONLYFULL-TIME CFOATA ADVISORY GROUP
Records what happenedYesYesYesYes
Forecasts cash weeks aheadNot typicallyPartlyYesYes
Measures built for your industryNot typicallyPartlyPartlyYes
Someone accountable for recommendationsNot typicallyNot typicallyYesYes
Works alongside your bookkeeper and CPANot typicallyNot typicallyPartlyYes
Lender-ready reportingNot typicallyPartlyYesYes
Typical costMonthly feeMonthly subscription$200,000+ a yearA fraction of a full-time CFO
● yes · ◐ partly · — not typically
BEGIN WITH A HEALTH CHECK

An honest look at where your business stands.

A complimentary review of your last twelve months, prepared by an advisor. Engagement options and fees are discussed afterward — only if there is a clear fit.

  1. Connect securely
    Read-only access to QuickBooks takes a few minutes; nothing in your books changes.
  2. Advisor review
    Your health score, strengths, risks and the most valuable lever — reviewed before you see it.
  3. A 30-minute conversation
    What the numbers mean, what we would focus on first, and whether working together makes sense.
Request a Health Check
An advisor and an owner reviewing a sample month-end cash chart on a laptop
WHO WE SERVE

Owner-led businesses, measured by what matters in their industry.

Each engagement starts from an industry playbook — the handful of measures that decide how a contractor, a restaurant or a clinic is really doing.

MAIN STREET

Service and trade businesses

Cash through slow seasons, pricing that keeps up with costs, staffing you can afford.

FOUNDERS

Early-stage companies

Runway you can trust, the true cost to win a customer, investor-ready reporting.

GROWING

Ready for the next step

Budgets, lender packages and covenants, and acquisition analysis.

A chef plating a dish, a contractor reading blueprints and a clinic reception desk

Industries with a playbook

  • Home & trade services
  • Construction & contractors
  • Restaurants & hospitality
  • Professional services
  • Healthcare & dental practices
  • Retail & e-commerce
  • Wholesale & distribution
  • Contingency-fee firms

When owners typically call us

  • Growing faster than cash allows
  • Preparing to borrow or refinance
  • Considering a hire, location or acquisition
  • Books that don’t yet tell a clear story
IN OUR CLIENTS’ WORDS

Results, in their own words.

“Our bank wanted a 13-week cash flow forecast before renewing our line of credit. That used to cost me a weekend in spreadsheets. ATA built it from our own books in a day — and the banker’s questions were answered before he asked them.”
Managing partner, law practice · Texas
“Every month I get the numbers I actually run the business on — margins by product line, who is paying slowly, where cash will be in a few weeks — within days of the close, not a month later.”
Owner, oil & gas supply company · Texas
QUESTIONS OWNERS ASK

Straight answers.

Do we need a CFO at our size?

If you’re making decisions about pricing, hiring or borrowing, yes — and a monthly advisory relationship gives you that judgment for a fraction of a full-time salary.

How is this different from our bookkeeper or CPA?

They record the past and handle tax. We use those numbers to help you decide what comes next — and we work alongside them, not instead of them.

What if our books are messy?

Most are. The Health Check shows what needs attention first, and we coordinate any clean-up with your bookkeeper.

What does a typical month look like?

Your numbers are updated as the books close, you receive a short written summary of what changed and why, and we meet to agree on the next steps — with a plan and owners for each.

FOR BOOKKEEPERS, CPAS AND LENDERS

We work alongside your trusted advisors.

Your bookkeeper keeps the books and your CPA handles tax. We bring forward-looking analysis and a clear monthly plan — and send questions their way, not work away from them.

Information for partners →

Read-only connections

We never move money or change your books.

Encrypted and private

Your data is never sold and never used to train AI.

A person signs off

Technology does the busywork; your advisor approves every figure and recommendation.

Independent advice

No commissions from software vendors, lenders or providers.

A CONVERSATION, NOT A PITCH

What’s your most valuable profit lever?

A Health Check answers that from your own numbers — then we talk about what’s ahead for your business.